Authorized Users on Business Credit Cards: A Guide for Crypto and Web3 Startups
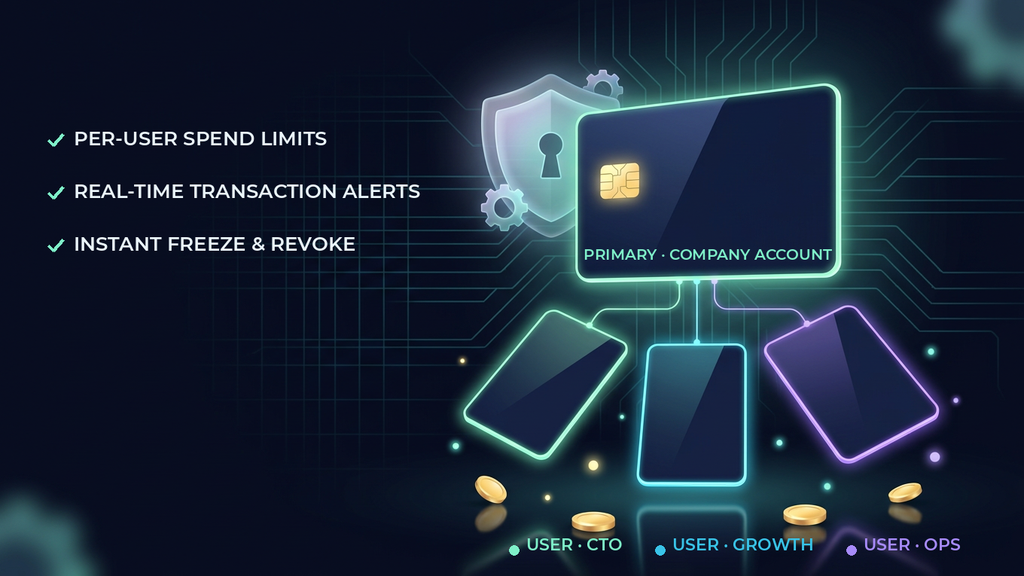
Your first hire just started, and she needs to pay for a hackathon booth by Friday. Handing over your own card number is a bad idea. Setting up an authorized user business card is usually the faster and safer fix. However, crypto and Web3 companies face a few extra wrinkles that a typical small business never sees. This guide walks through the liability, the credit reporting, the real fees in 2026 and the crypto-specific traps, so you can issue cards to your team without creating a new problem.
Why This Question Is Back on Crypto Founders’ Desks
For years, many crypto startups simply avoided bank-issued cards. Some were turned away. Others never applied because they expected a rejection. That picture is shifting in 2026.
On April 7, 2026, the OCC and the FDIC issued a joint final rule that bars both agencies from using “reputation risk” against the banks they supervise. The rule took effect on June 9, 2026. In addition, both agencies adopted another final rule on August 27, 2026 that tells examiners to focus on material financial risks. You can read the agencies’ own text in the OCC and FDIC final rule on reputation risk.
None of this forces a bank to approve your company. Card issuers still run their own credit and compliance reviews. Still, founders who gave up on traditional issuers are applying again. Meanwhile, the corporate card market has consolidated too. Capital One closed its acquisition of Brex on April 7, 2026, which changes the ownership behind one of the best-known startup cards.
As a result, more Web3 teams now face the same practical question this autumn. Once the account is open, how do you put cards in your team’s hands safely?
Three Ways to Give Your Team a Card
People use “authorized user,” “employee card” and “corporate card” as if they meant the same thing. They don’t. The differences decide who pays, whose credit takes the hit and how much control you keep.
| Option | Who is liable | Personal guarantee | Typical underwriting | Best fit |
|---|---|---|---|---|
| Authorized user on the owner’s business card | The business and the guarantor | Usually yes | Owner’s personal credit plus business details | Teams of 1 to 10 with a founder who has strong credit |
| Employee card with spending limits | The business and the guarantor | Usually yes | Same account, separate cards per person | Small teams that need per-person limits |
| Corporate card platform (Ramp, Brex) | The company | No, for qualifying companies | Cash balance and cash flow | Funded or cash-rich startups |
In practice, most small-business issuers treat “employee card” as their name for an authorized user. Chase’s card terms, for example, state that any employee allowed to use the account becomes an authorized user. That employee also gets equal charging privileges unless you set individual limits. That detail alone should shape your setup.
Corporate card platforms work differently. Ramp and Brex underwrite on your company’s bank balance rather than your personal score. Current eligibility thresholds sit around $25,000 in cash for Ramp and $50,000 for Brex. Neither platform accepts sole proprietors or unregistered businesses. If your token project still runs through a personal account, fix the entity structure first.
Who Pays When an Authorized User Business Card Is Misused
This is the part founders skip, and it is the part that hurts most later. On a standard small-business card, the person who signed the personal guarantee owns every charge. That includes charges an employee made, approved or not.
Citi puts it plainly in its own guidance. Most business cards require a personal guarantee, so the cardholder must repay all account charges, including employee charges. If the business can’t pay, the guarantor’s personal credit can suffer.
What federal law actually protects
Business cards fall mostly outside the consumer protections of the Truth in Lending Act. However, two rules in Regulation Z still apply to business cards. The first limits how issuers can send out cards. The second caps liability for unauthorized use at $50, provided certain conditions are met.
There is a catch for growing teams. Under 12 CFR 1026.12(b)(5), if an issuer provides 10 or more cards to one organization’s employees, the issuer and the company may agree to different liability terms. In other words, your contract can expose the company to more than $50 per incident. The same rule still protects the individual employee, though. Neither the issuer nor the company can push liability onto that employee beyond what the regulation allows. You can read the exact wording in the federal Regulation Z rule on unauthorized card use.
Unauthorized use vs. misuse
Here is the distinction that matters. “Unauthorized use” means someone used the card without actual, implied or apparent authority. An employee you handed a card to has authority. So if your ops lead books a $4,000 conference trip you never approved, the law generally treats that as an internal dispute. It is not fraud the issuer must absorb. Because of this, spending limits and written policies do the real protective work.
Does an Authorized User Business Card Affect Personal Credit?
The honest answer: it depends on the issuer, and the rules differ for you and for your employees.
For the owner, most business cards stay off personal credit reports while the account is in good standing. Some issuers break that pattern. Ramp’s analysis notes that most Capital One Spark business cards report full activity to the personal bureaus. So a big month of event spending could raise your reported utilization even if you pay in full. Other issuers report only negative events, such as serious delinquencies.
For employees, the impact is usually small. Card issuers generally don’t pull an employee’s credit when adding them as an authorized user. Experian also states that it does not include missed payments on authorized user accounts in the authorized user’s credit report. That said, an employee whose SSN was collected could still see the account appear if the issuer reports it.
| Who | Hard inquiry when added | Card can appear on their report | Main risk |
|---|---|---|---|
| Founder or guarantor | Yes, at application | Depends on issuer | Default or high reported utilization |
| Employee authorized user | Usually no | Only if the issuer reports to consumer bureaus | Minor, mostly limited to balance reporting |
| Corporate card employee | No | Rarely | Almost none |
For a remote crypto team, this matters for hiring. Some candidates will ask whether a company card shows up on their credit file. Check your issuer’s policy before onboarding, and tell them the truth.
What Employee Cards Actually Cost in 2026
Fees vary far more than most founders expect. Here is what major options charge right now, based on issuer terms as of autumn 2026.
| Card or platform | Employee card fee | Notes |
|---|---|---|
| Chase Ink Business Unlimited, Cash, Preferred, Premier | $0 | Individual spending limits available (Chase employee card terms) |
| Amex Business Platinum: Employee Platinum Card | $400 per card per year | Up from $350; primary card fee is $895 |
| Amex Business Platinum: Employee Expense Card | $0 | Spend control without the Platinum travel perks |
| Ramp corporate card | $0 | Requires roughly $25,000 in cash; no personal guarantee |
| Brex (Capital One) | $0 on base tier | Requires roughly $50,000 in cash for funded startups |
The Amex line deserves a second look. Ten Employee Platinum cards would add $4,000 a year on top of the $895 primary fee. That might make sense for two founders who fly to every major conference. For a support team, the free Expense Card does the same job.
These figures change often. Issuers adjust fees with little notice, so confirm the current rates and fees page before you add anyone.
The Crypto-Specific Traps Most Guides Miss
General small-business advice stops here. Crypto teams, however, run into problems that a bakery or a design agency never meets.
Trap 1: Crypto purchases may be blocked or treated as cash advances
Many issuers treat crypto purchases as cash-like transactions. Some card networks have coded digital currency purchases in a way that triggers cash advance treatment. That usually means an upfront fee, interest from day one and no rewards. Several large issuers, including Chase and Capital One, have blocked crypto purchases on their cards entirely, according to multiple industry reports.
The practical rule is simple. Never let an employee buy tokens, gas fees or testnet faucet top-ups with the company card. Fund wallets through your business bank account or your exchange account instead. Then document every transfer for your books.
Trap 2: Paying the card with crypto creates a tax event
Some founders plan to sell treasury tokens to pay the monthly card bill. That is allowed, but it isn’t neutral. Under IRS rules, selling or exchanging a digital asset is a taxable disposition. Every sale to cover a card statement needs a recorded cost basis and a gain or loss. If your team expenses heavily, this can turn into dozens of small taxable events a year.
Trap 3: Global contributors and DAO members
Web3 teams are often spread across many countries. Some contributors are contractors, and some are DAO members paid in tokens. Card issuers generally expect authorized users to have a real business relationship with your company. Chase’s terms, for instance, require you to confirm that the business has a relationship with each cardholder and permission to share their information. Adding a pseudonymous contributor you have never verified can put the whole account at risk.
Trap 4: Software and infrastructure spend that never stops
Crypto startups pay for RPC nodes, cloud servers, indexers and audit tools. These are recurring charges, often in large amounts. If an engineer signs up for a node provider on an authorized user card and then leaves, the charges keep running. Use virtual cards or a dedicated card per vendor so you can cut one subscription without freezing a person.
A 7-Step Checklist for Setting Up Your Team
Use this list before you add your first authorized user business card holder. It takes an afternoon, and it saves weeks of cleanup.
- Confirm your entity and EIN. Corporate platforms reject sole proprietors, and most issuers want a registered business. Put the account in the company’s name.
- Choose the right product for your stage. A strong founder credit profile and a small team point to an issuer card with free employee cards. A funded team with $50,000 or more in cash can look at corporate platforms with no personal guarantee. Our guide on how to pick the right card for your spending explains the trade-offs in more depth.
- Set a limit for every card on day one. Without limits, many issuers give employees the same charging power as the account owner. Start low and raise limits after 60 days of clean spending.
- Write a one-page spending policy. List allowed categories, receipt deadlines and banned purchases. Ban crypto purchases, personal spending and cash advances explicitly.
- Collect receipts within a fixed window. An IRS accountable plan requires a business purpose, adequate records within a reasonable time and the return of any excess. Set a 30-day receipt rule so you stay well inside that window.
- Separate crypto rails from card rails. Keep token purchases, wallet funding and on-chain payments outside the card program. If you want crypto rewards on spending, compare options in our review of the best crypto credit and debit cards instead of forcing it through a standard card.
- Build an offboarding step. Cancel the departing person’s card the same day their access ends. Then move any recurring vendor charges to a new card before the next billing date.
Review your setup every quarter
A quarterly check keeps the program honest. Look at total spend per person, declined transactions and any charges coded as cash advances. Next, compare your fees against current issuer terms. Finally, confirm that every active cardholder still works with you. Fifteen minutes each quarter usually catches problems before they reach your personal credit.
When an Authorized User Business Card Is the Wrong Tool
Sometimes the right answer is not to add anyone. Consider these cases.
If you have one contractor who spends twice a year, reimbursement is simpler. If your startup holds most of its runway in stablecoins rather than dollars, a bank may struggle to underwrite you. In that case, a corporate platform that looks at your bank balance may still need dollars on deposit. Similarly, if your founder’s personal credit is thin, a personal guarantee puts too much risk on one person.
On the other hand, an issuer card with free employee cards fits a lean, US-based team well. You keep the rewards, you set the limits and you see every charge in one place.
Five Questions to Ask the Issuer Before You Apply
A short call with the issuer’s business team answers most of the unknowns above. Ask these questions before you sign anything.
Do you report business card activity to consumer bureaus? The answer tells you whether heavy months will show up on your personal file. Ask about both positive and negative reporting.
What information do you need for each employee? Some issuers want a name and date of birth. Others also ask for an SSN, which can affect whether the card appears on that person’s report.
How do you code crypto exchange transactions? You want to know whether they are blocked, treated as cash advances or processed as purchases. Get the answer in writing if you can.
Can I set limits by person and by merchant category? Per-person limits are standard now. Category controls are rarer on issuer cards, yet they matter for a team that pays many software vendors.
What happens to rewards earned on employee cards? On most accounts, the primary cardholder collects every point. Confirm that before you promise anyone a perk.
The Bottom Line
Adding people to your company card is easy. Doing it without exposing your personal credit, your tax records or your treasury takes a bit of planning. Start with the entity, pick the product that matches your cash position and limit every card from the start. Above all, keep crypto purchases off the card program entirely.
The regulatory mood toward crypto banking improved in 2026, but issuers still judge each application on its own risk. A clean, well-documented card program is one more signal that your startup is a safe customer.
This article is for general information only and is not legal, tax or financial advice. Card fees and issuer policies change frequently; confirm current terms with the issuer before applying. Data as of October 2026.