Full-Stack Neobank vs. Partner-Bank: The Real Risk
In April 2024, over 100,000 neobank customers woke up locked out of their own money. Every account said “FDIC insured.” That label didn’t save them. This single event explains, better than any theory could, why the difference between a full-stack neobank and a partner-bank neobank matters far more than most people realize.
This guide breaks down what that distinction actually means. It also walks through exactly what went wrong for those 100,000 customers, and shows you how to check which model your own neobank uses.
What “Full-Stack” Actually Means
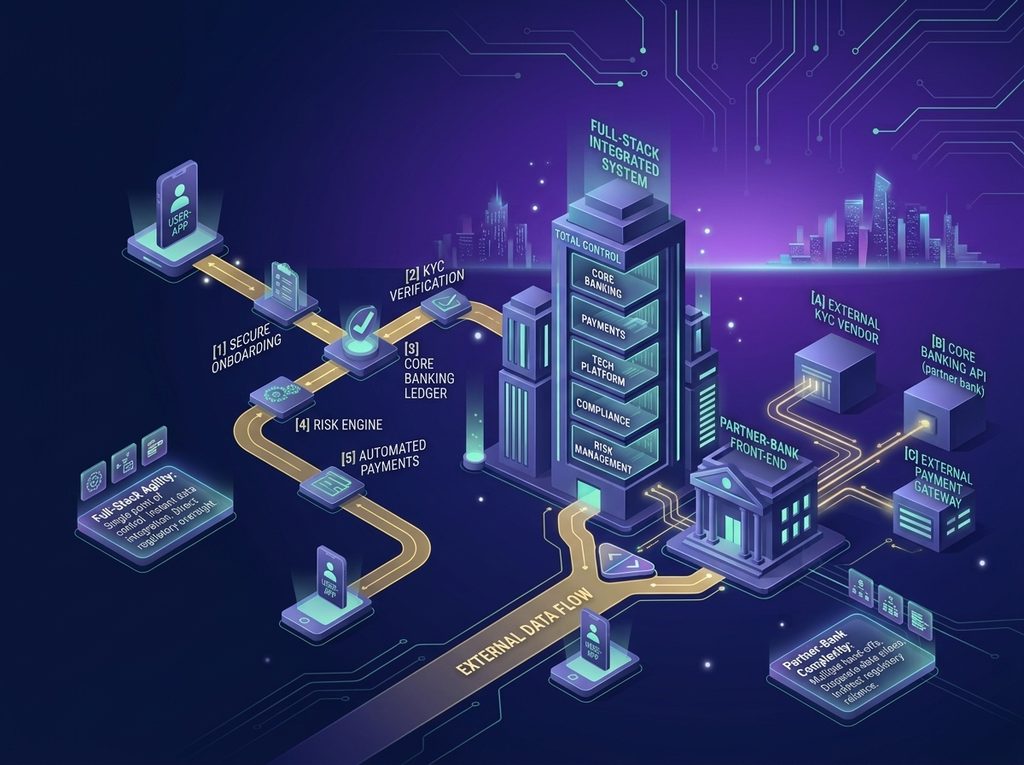
A full-stack neobank holds its own banking charter directly. It doesn’t rely on a separate, traditional bank behind the scenes to hold your deposits. SoFi obtained its own national bank charter in 2022. Varo went even further. It became the first US consumer fintech to receive its own banking charter back in 2020. When you deposit money with either company, that bank itself holds your funds. No third party sits in between, and the bank reports directly to federal regulators.
What “Partner-Bank” Actually Means
Most neobanks don’t hold their own charter. Building a bank from scratch is expensive and slow. Because of this, most fintech startups instead partner with an existing, chartered bank behind the scenes. Chime works this way, relying on partner banks to actually hold customer deposits while Chime itself handles the app, marketing, and customer relationship. This model isn’t inherently dangerous. In fact, it’s how the vast majority of neobanks operate. However, it introduces an extra layer between you and your money. That extra layer is exactly where things went catastrophically wrong for one group of neobank customers.
The Synapse Collapse: What Actually Happened
Here’s the case study that makes this distinction concrete instead of theoretical. A company called Synapse Financial Technologies operated as middleware, connecting roughly 100 different fintech apps to a handful of FDIC-insured partner banks behind the scenes. Neither the fintech apps nor most of their customers thought much about Synapse at all. It just quietly handled the ledgering, tracking which portion of a partner bank’s pooled account belonged to which individual customer.
Synapse filed for bankruptcy in April 2024. Within weeks, its partner banks lost access to Synapse’s own records. They could no longer reliably tell which customer owned which portion of the money sitting in their pooled accounts. Roughly $265 million in customer funds froze overnight, affecting fintech apps including Yotta, Juno, and Copper.
The Human Cost Behind the Numbers
The individual stories from this collapse illustrate the real stakes. One former schoolteacher from Texas had deposited more than $282,000 into a fintech app called Yotta. She eventually recovered just $500 of it. Other Yotta customers with over $10,000 on deposit received less than a single dollar back. More than two years later, some affected customers still haven’t been made whole. A court-appointed trustee later identified a shortfall of $65 million to $95 million between what Synapse’s records showed and what banks actually held. No single party has accepted clear responsibility for making customers whole.
Why “FDIC Insured” Didn’t Protect These Customers
This is the part that catches people off guard. FDIC insurance protects your deposits if the bank itself fails. It doesn’t automatically protect you if the middleware company tracking which customer owns which portion of a pooled account fails instead. The partner banks in the Synapse case were themselves solvent and FDIC-insured. The real problem was different: nobody could reliably reconstruct whose money was whose once Synapse’s ledgering system became unreliable. Researchers studying the collapse call this the “weakest-link problem” in fragmented banking-as-a-service arrangements. It only takes one broken link in the chain, even one that isn’t a bank at all, to trap customer funds indefinitely.
Does This Mean Partner-Bank Neobanks Are Unsafe?
Not automatically, and it’s important not to overcorrect here. Millions of customers use partner-bank neobanks every day without incident, and the model itself isn’t inherently broken. Chime, for example, wasn’t among the fintech apps affected by the Synapse collapse. The real lesson isn’t “avoid partner-bank neobanks entirely.” Instead, it’s “understand which model you’re using, and know exactly which bank actually holds your money.”
How to Check Which Model Your Neobank Uses
Look for a specific bank name in your neobank’s terms of service or FAQ page. It’s usually phrased as something like “deposits are held at [Bank Name], Member FDIC.” If you can immediately name that specific bank, you’re using a partner-bank model, and that’s fine as long as you also know it. If your neobank holds its own charter instead, like SoFi or Varo, its own name appears as the actual bank, since no separate middleman institution exists to identify. If you genuinely can’t find a clear answer either way, treat that itself as a caution sign about the platform’s transparency.
Practical Steps to Protect Yourself Either Way
First, avoid concentrating your entire emergency fund or a large, irreplaceable sum in a single fintech account chasing a slightly higher advertised interest rate, particularly with a lesser-known partner-bank neobank. Our guide to the best high-yield savings accounts covers several established options if you’re comparing where to actually keep meaningful savings. Second, understand that in-app “vaults” or “pockets” within a savings feature sometimes function as sub-ledgers inside one larger custodial account, rather than as individually insured accounts of their own. This distinction matters enormously if something ever goes wrong upstream. Third, diversify meaningfully important savings across more than one institution rather than trusting a single platform with everything, a sensible practice regardless of which banking model you’re using.
Why This Matters More as Neobanks Keep Growing
Roughly 75 million Americans now use a neobank of some kind, up from fewer than 5 million in 2018. As that number keeps climbing, more everyday financial activity flows through this exact structure: chartered banks partnering with technology companies through middleware most customers never think about. Regulators have acknowledged gaps in how these arrangements get supervised. The Synapse case specifically pushed renewed attention toward tightening oversight of banking-as-a-service arrangements industry-wide. Until regulation catches up fully, understanding this distinction yourself remains the most reliable protection available.
The Bottom Line
The difference between a full-stack neobank and a partner-bank neobank isn’t abstract industry jargon. It’s the difference between your bank directly holding your money under its own charter, and a chain of separate companies, including at least one you’ve probably never heard of, standing between you and access to your own funds. Neither model guarantees safety or danger on its own. What matters is knowing which one you’re actually using, and treating that knowledge as a real factor in how much you’re willing to keep in any single account. We cover how to verify your specific FDIC coverage status directly in our companion guide on checking whether your neobank is actually FDIC insured. For the official rules governing how deposit insurance actually works, see the FDIC’s own guidance on deposit insurance.
FAQs
What is the difference between a full-stack neobank and a partner-bank neobank?
A full-stack neobank, like SoFi or Varo, holds its own banking charter directly. A partner-bank neobank relies on a separate, traditional chartered bank behind the scenes to actually hold customer deposits.
Was Chime affected by the Synapse collapse?
No. Chime was not among the fintech apps affected by Synapse’s 2024 bankruptcy. The affected companies included Yotta, Juno, and Copper.
Does FDIC insurance always protect neobank customers?
FDIC insurance protects deposits if the actual bank fails, but it doesn’t automatically protect customers if a separate middleware company tracking account ownership fails instead, as happened in the Synapse collapse.
How can I tell which model my neobank uses?
Check your neobank’s terms of service or FAQ page for a specific partner bank name, usually phrased as “deposits held at [Bank Name], Member FDIC.” If no clear bank name appears, or if the neobank’s own name appears as the chartered institution, that indicates a full-stack model instead.